What Is the Travel Bank: Smart Trip Credit
What is the travel bank sounds like a simple question, yet it usually pops up right after plans shift, flights change, or money gets stuck as credit instead of landing back on a card. That’s where the idea gets practical fast. A travel bank is generally a digital place where eligible travel credits, vouchers, or airline funds can sit until they’re used for another booking. Not glamorous, sure, but it can save a lot of head-scratching later.
Picture a canceled flight, a changed itinerary, or a ticket credit that doesn’t come back as cash. Instead of digging through old emails, confirmation numbers, and half-forgotten receipts, the travel bank keeps that value tied to an account or booking profile. That makes it easier to see what’s available, what rules apply, and where the credit can be used. The catch, of course, is that every provider can set its own limits, so the fine print still matters.
The biggest pain point is usually not the credit itself. It’s the messy trail that follows. Expiration dates, name restrictions, fare rules, and eligible routes can turn a simple credit into a tiny paperwork jungle. A clear understanding of what is the travel bank helps cut through that noise before a balance quietly expires or gets used the wrong way.
Travel credit also changes how people plan. A balance sitting in a travel bank account can nudge the next trip toward one airline, one platform, or one booking path. That can be useful if the credit fits the trip already in mind. But if the rules are narrow, it may feel like being handed a gift card to a store across town, technically useful, yet not always convenient.
Still, the upside is real. A travel bank can keep unused value visible, reduce the chance of losing track of funds, and make rebooking less annoying after plans go sideways. It works best when the balance is checked early, the expiration date is noted, and the terms are read before building a new itinerary around it. Small habit, big difference.
So, what is the travel bank in plain English? It’s a holding spot for travel value that may be used later under specific rules. It won’t magically erase restrictions, and it won’t always behave like cash. But handled carefully, it can turn a canceled plan into a useful head start on the next one.

- TLR Rank9.4
TLR Rank is a ranking system developed by TravelLuggageReviews.com. TLR Rank has no relationship or impact from any manufacturers or sales agent websites. Learn more
- BrandAntteez

- TLR Rank9.2
TLR Rank is a ranking system developed by TravelLuggageReviews.com. TLR Rank has no relationship or impact from any manufacturers or sales agent websites. Learn more
- BrandAnker

- TLR Rank9.2
TLR Rank is a ranking system developed by TravelLuggageReviews.com. TLR Rank has no relationship or impact from any manufacturers or sales agent websites. Learn more
- BrandNusyddy

- TLR Rank9.0
TLR Rank is a ranking system developed by TravelLuggageReviews.com. TLR Rank has no relationship or impact from any manufacturers or sales agent websites. Learn more
- BrandCoowisty

- TLR Rank9.0
TLR Rank is a ranking system developed by TravelLuggageReviews.com. TLR Rank has no relationship or impact from any manufacturers or sales agent websites. Learn more
- BrandCoowisty

- TLR Rank8.6
TLR Rank is a ranking system developed by TravelLuggageReviews.com. TLR Rank has no relationship or impact from any manufacturers or sales agent websites. Learn more
- BrandAnker
Last update on 2026-09-13 / Affiliate links / Images, Product Titles, and Product Highlights from Amazon Product Advertising API
What Is The Travel Bank
A canceled flight can turn a tidy travel plan into a messy pile of credits, emails, rules, and “wait, where did that money go?” moments. That’s where what is the travel bank starts to matter in a very practical way. A travel bank is usually a digital account or credit wallet where eligible travel funds sit until they’re used for a future booking. It sounds simple, but the details can get picky fast, especially around expiration dates, passenger names, eligible fares, and booking channels.
Travel Bank Basics
What is the travel bank is best answered in plain English: it’s a place where unused travel value can be stored for later. That value may come from a canceled flight, a changed reservation, a travel voucher, or a credit issued by an airline or travel provider. It is not always cash, and that difference matters. A travel bank balance often behaves more like store credit than money sitting in a regular bank account.
The biggest relief comes from having one visible place to check instead of hunting through old inbox threads. A travel credit account can show available funds, remaining balance, and sometimes the deadline for using them. That visibility helps prevent the classic “I forgot I had credit” problem. Still, the balance is only useful if the rules match the trip you’re trying to book.
Travelers often get tripped up because travel bank funds can feel flexible until the fine print shows otherwise. Some credits may only apply to flights, while others may exclude bags, seats, taxes, upgrades, or partner bookings. Some may be tied to the original passenger’s name. That’s why the smart move is to read the rules before treating the credit like a blank check.
A useful way to think about a travel bank is as a holding drawer for future travel value. It keeps credit from disappearing into scattered confirmation emails. But it doesn’t remove restrictions, extend deadlines automatically, or guarantee the cheapest fare. Used carefully, what is the travel bank becomes less confusing and a lot more useful during rebooking.
Why Travel Credits Feel So Confusing
The confusion usually starts because the word “bank” sounds more flexible than it really is. A normal bank account lets money move almost anywhere, but a travel bank usually keeps value locked inside a travel system. That means the funds may only work on one airline, one booking website, or one type of purchase. Annoying? Sometimes, yes. But knowing that upfront saves plenty of frustration.
Another headache comes from mixed language. Airlines and booking platforms may use terms like flight credit, voucher, wallet, future travel credit, or travel bank balance. Those names can overlap, but they don’t always follow the same rules. A voucher might need a code, while a travel bank balance may appear automatically after logging in. Small difference, big booking-day impact.
Expiration dates create the most pressure. A travel bank credit may expire based on the issue date, the original ticket date, or a policy listed in the account. Miss that detail, and the value may vanish even if the trip was never taken. That’s why setting a reminder right after receiving credit is one of those boring little habits that actually pays off.
Names and transfer rules add another layer. A balance may be attached to the traveler who held the original ticket, not the person who paid for it. That can sting when a parent, partner, or friend covered the cost but can’t use the credit later. Before planning around unused travel funds, check whether the credit is transferable, shareable, or locked to one traveler.
How A Travel Bank Helps After Plans Change
Plans fall apart for ordinary reasons: work shifts, family needs, weather delays, sick kids, missed connections, or a route that no longer makes sense. A travel bank can soften the blow by keeping some value available instead of letting the whole booking feel wasted. That matters because travel costs don’t always come back as a clean refund. Sometimes the practical win is simply keeping the credit visible and usable.
The strongest benefit is control. With a travel bank balance, you can often apply funds when a new trip makes sense instead of rushing into a bad replacement booking. That flexibility helps if prices are high today but may calm down later. It also helps keep decision-making grounded instead of emotional, which is handy after a cancellation already made everyone cranky.
There’s a tradeoff, though. Credit can nudge you toward the same airline or travel provider, even if another option has a better route or lower fare. That’s not always bad, but it can quietly shape the next trip. A smart traveler compares the total cost after applying the travel credit, not just the out-of-pocket amount at checkout.
Trip preparation still matters once the credit is sorted. A stuck handle or damaged suitcase can turn airport timing into a circus, so fix the small stuff before departure with this practical fix stuck suitcase handle guide. That kind of prep pairs well with managing a travel bank because both reduce last-minute stress. Less scrambling, fewer surprises, better odds of starting the trip with your head on straight.
Rules That Matter Before You Rebook
Before using a travel bank, check what the credit can actually buy. Some balances apply only to base fares, while taxes, fees, bags, and seat selections may need another payment method. Other credits may work on bundled fares or vacation packages, but only through a specific booking path. The key factor is eligible use, not just the balance amount.
The second rule is the deadline. A travel bank expiration date can be easy to miss because it may not sit front and center during every login. Write it down somewhere you’ll actually see it, not in a random note that gets buried. A credit that expires unused is basically a lesson with a price tag. Nobody needs that lesson twice.
Passenger rules deserve close attention too. Some travel funds stay locked to the original traveler, even if someone else paid. That can affect families, group trips, and shared bookings in a hurry. Before building a new itinerary around future travel credit, confirm whose name must appear on the reservation.
Authenticity and account safety also deserve a quick nod. Travel credits, luxury bags, and online purchases all share one uncomfortable truth: details matter. For resale or gift planning around trip gear, protect your money with this helpful check authentic coach bag guide before trusting a listing. The same careful mindset helps with travel bank funds, especially if emails, codes, or account notices look suspicious.
Using Travel Bank Funds Without Wasting Value
The best use of a travel bank starts before checkout. Log in early, confirm the balance, read the terms, and compare routes before committing. That sounds obvious, but rushed rebooking is where small mistakes sneak in. A few calm minutes can protect unused travel value from being spent poorly.
Price comparison still matters after credit appears. A flight may look cheap because the travel bank balance lowers the final payment, but the original fare could still be higher than another option. Run the math both ways. If the credit forces a pricier route, the “savings” may not be as sweet as it looks.
Partial payments can be useful if the system allows them. Some platforms let a travel credit cover part of the fare while another card pays the rest. That can stretch the value across a trip without forcing awkward choices. But if the full credit must be used in one transaction, choose the booking carefully so leftover value doesn’t get trapped or lost.
Packing choices can also affect how smoothly a credit-funded trip feels. Japan, for example, rewards lighter bags, clean organization, and luggage that behaves well on trains and tight hotel rooms. For a smarter packing setup, compare options through this best carry on luggage for japan resource before locking in the final trip details. A good travel bank plan covers the booking, while good luggage keeps the actual movement from becoming a daily chore.
Common Mistakes That Shrink Travel Bank Value
The first mistake is assuming a travel bank works like cash. It usually doesn’t. Credits can be limited by airline, account, traveler name, route, fare type, or booking deadline. Treating the balance like regular money leads to disappointment at the payment screen.
The second mistake is waiting too long. A travel bank credit may seem safely stored, but expiration dates don’t care how busy life gets. The best habit is checking the balance shortly after it’s issued and setting a calendar reminder well before the deadline. That buffer gives you time to plan instead of grabbing a random trip just to avoid losing value.
The third mistake is ignoring the total trip cost. A credit may cover the flight, but bags, hotel nights, airport transfers, food, and schedule changes still count. A “free” ticket can become expensive if the route is awkward or lands at a bad time. Smart use of future travel funds means looking at the whole trip, not only the checkout total.
The last mistake is losing track of confirmation details. Keep the email, account login, credit amount, issue date, and rules in one place. Screenshots help, but they shouldn’t replace checking the live account before booking. A tidy record makes what is the travel bank feel less like a mystery and more like a tool you can actually control.
How Travel Bank Credit Works For Smarter Rebooking
A leftover credit can feel useful one minute and oddly annoying the next, especially after the original trip has already been canceled, delayed, or reshuffled. The real value comes from treating travel bank credit like a planning tool instead of a random leftover balance. That means checking the rules before chasing fares, matching the credit to a trip that already makes sense, and keeping the booking simple enough that the value doesn’t get eaten by extra fees. Used with a clear head, what is the travel bank becomes less about airline jargon and more about protecting money that already belongs in the next trip.
The tricky part is that travel credit rarely feels as clean as cash. A balance may sit in an airline account, but the actual use can depend on fare type, passenger name, expiration date, route, and booking platform. That can be frustrating, sure, but it’s manageable once the rules are treated like trip details rather than fine print to skim later. A good rebooking plan starts with the credit, then checks whether the route, timing, and final price still make sense.
Many people lose value because they rush to use the balance before asking the boring but necessary questions. Can the credit cover taxes or only the base fare? Does it work for one traveler or everyone on the booking? Can it be split across trips, or does it need to be used all at once? These small details decide whether a travel bank balance saves money or quietly boxes the trip into a corner.
Planning the physical side of travel matters too, because a credit-funded trip can still become a headache if the bag is bulky, awkward, or hard to lift. For shorter trips where overhead-bin space and easy movement matter, compare a practical 20 inch carry on before building the whole packing list. A compact bag can pair nicely with travel bank rebooking because it keeps the trip lean, especially when the new itinerary has tight transfers or smaller aircraft. Less bulk gives the credit a better chance to feel like a real win instead of one more travel compromise.
How To Read Travel Bank Rules Without Getting Burned
Travel bank rules can look harmless until the payment page refuses the balance or applies only part of it. That moment stings because the trip already feels planned in your head. The safest move is to read the eligible purchase rules before comparing flights. A few lines about fare use, passenger restrictions, or booking channels can change the whole plan.
Start with the expiration date because that’s the rule most likely to cause a last-minute scramble. Some credits expire by a specific calendar date, while others may follow a policy tied to the original ticket. A travel bank expiration should go into a calendar reminder right away, ideally with enough room to book calmly. Waiting until the final week can force a bad route, a bad fare, or a trip nobody is excited about.
Next, check whether the credit is tied to a person. A family trip can get awkward if the person who paid cannot use the balance because the credit belongs to the named traveler. That happens more often than people expect. A name-locked travel credit is still useful, but only if the next booking includes the right traveler.
Then look at what the credit can cover. Some balances may apply to airfare but not baggage, seat selection, upgrades, or partner services. Others may require direct booking through the airline account where the travel bank funds are stored. That’s why copying the rules into a note can be surprisingly helpful, especially if the trip won’t be booked right away.
Why The Cheapest Fare Is Not Always The Best Use
A cheap fare looks tempting when a travel bank balance is sitting there, but the lowest sticker price can hide the wrong trip. Maybe the flight leaves too early, lands too late, or adds a connection that turns a simple weekend into a long airport shuffle. Credit should reduce stress, not create a schedule nobody wants. A better question is whether the final itinerary fits the purpose of the trip.
Some travelers accidentally spend credit just because it exists. That can lead to booking a route that burns time, adds hotel costs, or creates baggage fees that wipe out the savings. A smart travel credit strategy compares the whole trip cost, not only the checkout number after the balance is applied. The fare, timing, luggage, transport, and flexibility all belong in the same math.
There is also a mental trap here. Credit can feel like “free money,” even though it came from a trip already paid for. That mindset can make a mediocre booking feel acceptable. Treat the travel bank credit as real value, and the decision gets clearer fast.
For longer routes or checked-bag trips, luggage can affect both cost and comfort more than expected. A soft-sided checked bag may give extra flexibility for odd-shaped items, so review a sturdy soft side checked luggage option before assuming a carry-on setup will handle everything. The point is not to buy more gear for no reason. The point is to match the booking, the baggage rules, and the travel bank value so the trip works in real life.
How To Keep Travel Bank Credit From Expiring
Expiration is the quiet thief of travel bank funds. The balance may sit neatly in an account, but that doesn’t mean it will wait forever. A simple reminder system can protect the value without turning trip planning into a spreadsheet marathon. Put the deadline somewhere visible, then add an earlier reminder for route research.
A good habit is to check the balance after any cancellation or schedule change. Do not assume the credit posted correctly just because an email said it would. Log in, confirm the available travel credit, and save the details. If something looks wrong, it’s easier to question it early than months later.
Another useful habit is pairing the credit with trips already likely to happen. Visiting family, attending an event, or taking a planned vacation gives the balance a real destination. Randomly inventing a trip just to use credit can work, but it often leads to rushed choices. A travel bank plan should fit life, not pressure life into fitting the credit.
Keep an eye on policy updates too. Airlines and travel platforms sometimes adjust rules after major disruptions, schedule changes, or operational shifts. That doesn’t mean every credit gets special treatment, but it does mean checking the account before giving up. A few minutes of review can save a future travel balance from being written off too soon.
How Travel Bank Credit Fits Into A Bigger Trip Budget
A flight credit can make a trip feel cheaper, but the rest of the budget still has a say. Hotels, food, local transport, checked bags, seat fees, and schedule gaps can all change the real cost. A travel bank helps most when it lowers a trip that was already sensible. It helps less when it tempts someone into a route that creates new expenses.
Think of the credit as one piece of the booking puzzle. A balance might cover a flight, but a bad arrival time could require an extra hotel night. A cheaper route might need paid bags or a long ride from a distant airport. Those add-ons can chip away at the travel credit benefit before the trip even starts.
There’s also the comfort budget, which people often ignore until they’re tired and annoyed. A better-timed flight may cost more upfront but protect sleep, reduce transfer stress, or make the first day usable. If the travel bank balance makes that better schedule affordable, that can be a smarter use than chasing the absolute lowest fare.
The best decisions usually come from comparing two or three realistic options. Check the out-of-pocket cost, total travel time, baggage needs, and deadline pressure. Then ask which option uses the unused travel value without adding a pile of hidden friction. That practical view keeps the credit working for the trip instead of the other way around.
What To Do If Travel Bank Credit Does Not Apply
A credit that refuses to apply at checkout can make anyone mutter at the screen. Before assuming the balance is gone, check the basics: login status, traveler name, eligible route, fare type, and expiration date. A travel bank error often comes from one small mismatch. Fixing that mismatch can be quicker than starting the search from scratch.
Try the booking through the provider’s direct website if the credit rules mention direct use. Some credits do not work through third-party booking paths. Others may require selecting a certain payment option or entering a voucher number in a specific field. The correct booking channel matters more than many travelers expect.
If the amount applies only partially, check whether taxes, fees, or add-ons are excluded. That can explain why the balance appears smaller at payment. It’s annoying, but it’s not always a technical problem. A partial travel credit can still be useful as long as the remaining cost is clear before purchase.
Customer support can help, but go in prepared. Have the original confirmation number, credit amount, issue date, traveler name, and screenshots ready. Clear details make it easier to explain the problem without starting from zero. A tidy record gives travel bank support less room for confusion and more room to solve the issue.
How To Decide If A Travel Bank Booking Is Worth It
The simplest test is whether the trip would still make sense without the credit. If the answer is yes, the travel bank balance is probably helping. If the answer is no, the credit may be pushing the decision too hard. That little gut check can stop a messy booking before it starts.
Look at the deadline, but don’t let it bully the whole plan. An expiring credit deserves attention, not panic. Sometimes using part of the value on a modest, useful trip beats forcing the full balance into an awkward itinerary. A balanced rebooking choice protects money and sanity at the same time.
Comfort, timing, and baggage should sit beside price in the decision. A flight that saves a little money but creates a brutal layover may not be worth it. A slightly higher fare that uses the credit cleanly and keeps the day manageable can be the better call. Travel bank value is not just the dollar amount, it’s the hassle it helps remove.
Read the last screen before paying. Confirm the credit applied, the traveler names are correct, the remaining balance makes sense, and the new trip details are right. Then save the confirmation and any leftover travel credit details immediately. That final check is boring, yes, but boring is beautiful when it prevents another round of credit confusion.


9 Best Travel Camping Table of 2026 For Uneven Ground
12 Best Heavy Duty Camping Table of 2026 That Will Not Wobble or Sag
10 Best Sleeping Bags For Tall People of 2026 To Stretch Out Fully
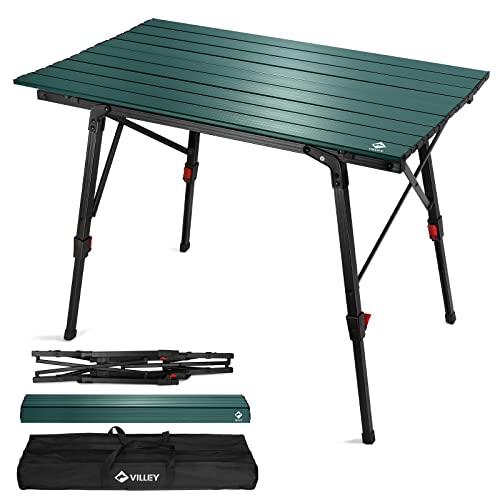
8 Best Camping Table Adjustable Legs of 2026 for Uneven Ground

10 Best Diaper Bag Backpacks For Dads of 2026 With Fast Gear Access

11 Best Framed Luggage of 2026 For Zipperless Security

11 Best Folding Two Wheeler For Luggage of 2026 To Prevent Tipping

11 Best Expandable Roller Luggage of 2026 That Fit Overhead Bins